A company’s corporate structure is not merely a technical or legal matter. It is a business decision that can directly affect growth, fundraising and international operations. Israeli companies working with investors, customers or partners outside Israel are often required to reassess their holding structure, especially before raising capital from foreign investors, expanding into the U.S. market, bringing in a strategic partner, listing abroad or reorganizing international operations. One of the key steps in this context is a flip.
At first glance, a flip may appear to be a simple change in the holding structure, so that a foreign parent company is placed above the Israeli company. In practice, it is a process that requires careful analysis of business, legal and tax aspects, and often coordination among several professional advisers at the same time. It is therefore important to understand not only what a flip is, but also when it is appropriate, what risks it creates, and how to prepare for it properly.
The purpose of this article is to provide clarity and explain what a flip is, why companies carry out a flip, what the Israel Tax Authority tends to examine, and how to prepare so that the process is sound from a business, legal and tax perspective
What Is a Flip?
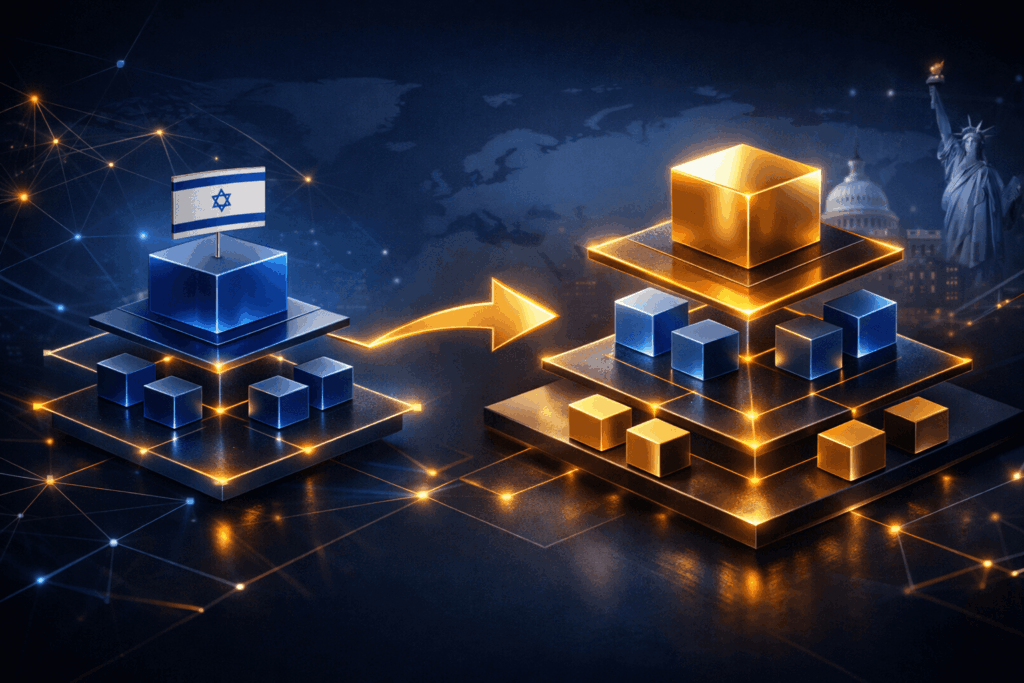
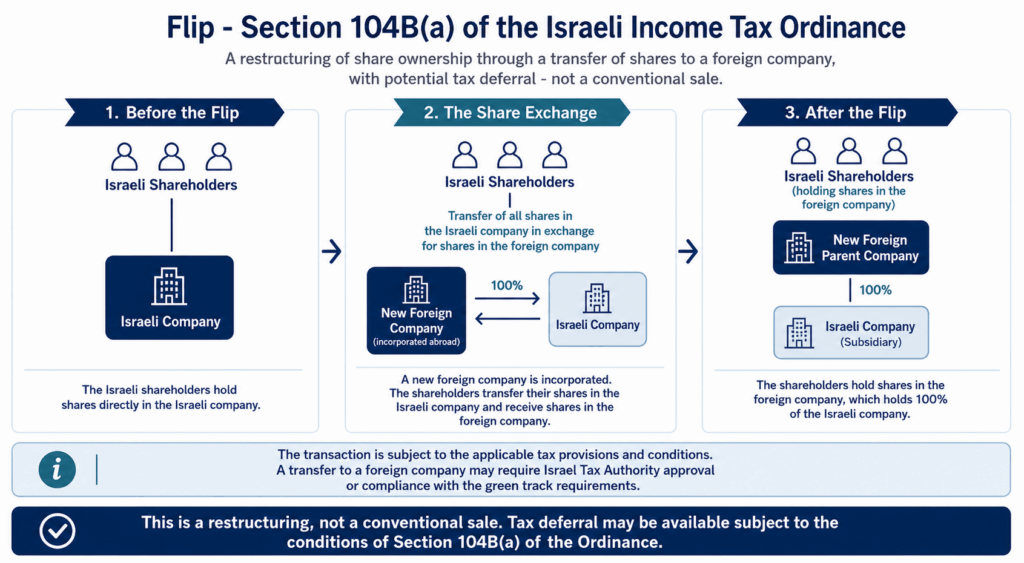
A flip is a restructuring in which a foreign parent company is added above the Israeli company.
Typically, the shareholders of the Israeli company transfer their shares to the foreign parent company and receive, in return, shares in the parent company. After completion, the Israeli company becomes a subsidiary of the foreign company. In simple terms: before the transaction, the shareholders hold shares directly in the Israeli company; after the transaction, they hold shares in the foreign parent company, which in turn holds the Israeli company. The transaction itself does not transfer the employees, business activity or intellectual property of the Israeli company abroad.
The Rationale Behind the Decision to Carry Out a Flip
The reasons for carrying out a flip vary from one company to another. Sometimes it is a requirement of foreign investors who prefer a familiar corporate structure. In other cases, it is driven by commercial considerations of customers, partners or financial institutions that prefer to engage with a foreign entity. There are also cases in which a flip is considered as part of preparations for a listing on a foreign stock exchange, a merger, an acquisition, a group reorganization or expansion into a key target market, particularly the United States.
In practice, a flip may be relevant both for startups and for established companies. Among startups, it is common ahead of financing rounds, the alignment of investment documents and option plan structures with international standards, and sometimes also in preparation for an exit. For established companies, it may form part of a group reorganization, the consolidation of international activity under a single holding company, the introduction of a strategic investor, or preparation for a significant transaction outside Israel.
That said, not every commercial difficulty or desire to appear more international justifies such a step. A flip is mainly appropriate where there is a clear business purpose and where it is planned properly. In suitable cases, it can help open doors with investors and customers, create corporate certainty and support international growth.
Does a Flip Create a Tax Event in Israel?
The transfer of shares in an Israeli company to a foreign parent company in exchange for the issuance of shares in the parent company may constitute a tax event, even if no cash consideration is received. Sections 104A and 104B of the Income Tax Ordinance establish routes that allow, subject to the conditions set out in them, the deferral of the tax liability arising from the transfer. Section 104A governs the transfer of an asset by an individual transferor, while Section 104B governs a transfer by several joint owners. Where the receiving company is a foreign company, application of the arrangement also requires the approval of the Israel Tax Authority. The arrangement allows for tax deferral while preserving tax continuity. It does not provide an exemption from tax that may apply upon the future realization of the shares.
In a structure involving a new company under Section 104B(a), the shareholders transfer all of their shares in the Israeli company to the parent company and receive shares only in return. The parent company must be incorporated specifically for the purpose of the transaction, without other assets or prior activity. At the time of the exchange, each shareholder’s relative holding and the relative value of the rights received must be maintained. For example, shareholders holding identical rights at rates of 60% and 40% will hold the same percentages in the parent company immediately after the exchange. The parent company is required to continue holding the shares of the Israeli company transferred to it for two years from the date of transfer.
In addition, the Israel Tax Authority examines the substance of the transaction, namely whether it is a genuine, consistent and documented transaction, and whether the documents align with the actual activity.
Amendment 279 to the Income Tax Ordinance, enacted in 2025, removed a significant barrier to capital raising after a flip. Previously, the shareholders who carried out the restructuring were required to continue jointly holding at least 25% of the rights in the company for two years from the date of the transaction. A financing round that diluted them below this threshold could have jeopardized the tax deferral arrangement. Following the amendment, this holding requirement was removed from Section 104B(a). As a result, dilution due to a capital raise or the issuance of new shares is not, in itself, a breach of the condition that was repealed. This is an important relief, particularly for startups planning significant financing rounds after the flip. However, the other requirements of the arrangement continue to apply: the foreign parent company must continue holding the shares of the Israeli company transferred to it for two years from the date of transfer. Under the relevant approval route, the company must also comply with requirements relating to the continuation of activity in Israel and the deposit of the shares of Israeli-resident shareholders with a trustee, in accordance with the terms of the tax ruling. It should not be assumed that the trust arrangement ends after the two-year period.
How Is a Flip Carried Out in Practice?
The process begins with a review of the company’s structure, the investors’ requirements and the transaction timeline. The shareholders, classes of shares, options and existing agreements are mapped, and the appropriate tax route is examined. Where the financing round depends on completion of the flip, it is important to plan the two processes together.
The next step is to choose the jurisdiction of incorporation and the type of foreign company. The choice should fit the needs of the investors and the planned activity, while also taking into account the tax implications and ongoing costs. With the assistance of professionals in the target jurisdiction, the company is incorporated, the share capital and shareholder register are arranged, and the required registrations are completed. In the case of a U.S. company, for example, this also includes obtaining a federal tax identification number, an Employer Identification Number (EIN).
The structure also includes a requirement for a trust arrangement. A trustee must therefore be engaged, and an appropriate agreement must be signed with the trustee. The trustee holds the rights and handles reporting and tax withholding in accordance with the tax ruling. We work with trustees accepted by the Israel Tax Authority in procedures of this kind and coordinate with them regarding the deposit requirements and documentation, subject to the arrangement approved.
At the same time, a share transfer and exchange agreement between the shareholders and the foreign company must be prepared, along with the required corporate approvals. It is advisable to work with lawyers in Israel and abroad on the drafting of the agreement. Where necessary, shareholders’ agreements and option plans are also updated, and intercompany agreements are put in place. It is important that all documents align with the structure presented to the Israel Tax Authority and with the trustee’s requirements.
We coordinate the tax aspects, prepare the application and annexes, and handle questions and follow-up requests from the Israel Tax Authority. After the required approvals are received, the share exchange is completed, the registers are updated, the rights are deposited with the trustee, and the reports are filed in accordance with the terms of the approval.
What Are the Costs of a Flip?
The cost depends on the jurisdiction of incorporation, the complexity of the share capital structure, the number of rights holders and the approval route. The main components to take into account are:
- An application fee payable to the Israel Tax Authority, according to the relevant route and the amount in effect on the filing date.
- Legal fees in Israel for the share exchange agreement, corporate approvals and required updates to existing agreements.
- Legal fees and service provider fees abroad for incorporation of the parent company, incorporation documents, share capital arrangements and local registrations.
- Trustee fees for setting up the trust arrangement, holding the rights, reporting and handling future events.
- Our fees for feasibility review, tax planning, preparation of the application and handling the process with the Israel Tax Authority, according to the agreed scope of work.
Where relevant, valuation, translation and document authentication costs may also be added. The ongoing costs of the foreign company should also be budgeted for, including fees, accounting and tax filings. It should not be assumed that all expenses of the transaction are deductible for tax purposes. Form 982 includes a provision denying the deduction of expenses related to the restructuring as an expense under Section 17 of the Ordinance.
Who May Benefit from a Flip – and Who May Not
A flip may be suitable for companies that have a genuine business need for an international structure, for example for raising capital from foreign investors, expanding into a key target market, introducing a strategic partner, carrying out a group reorganization or preparing for a significant transaction outside Israel. It may also be suitable where the existing structure no longer serves the company’s business strategy effectively.
By contrast, where there is no clear business purpose, where the main activity remains in Israel without a real need for a foreign structure, or where the complexity of the process exceeds the expected benefit, it may be preferable to consider other alternatives.
What Are the Main Risks of a Flip?
The first risk is an unplanned tax event, loss of tax deferral or exposure created by an action that was not coordinated properly. Sometimes the exposure arises specifically around a financing round, issuance or change in rights carried out after the flip without prior review of its implications.
Another risk concerns the future effects of the structure. Adding a foreign parent company may create a less efficient structure from a tax perspective: distributions of profits from the Israeli company to the parent company and from the parent company to the shareholders may be subject to tax and withholding tax in more than one jurisdiction, and full foreign tax credit may not always be available. The sale of the Israeli company by the parent company may also create a different tax outcome than a sale of the parent company’s shares by the shareholders. It is therefore important to examine not only the transaction date, but the entire life cycle of the structure, including dividend policy, a future sale, funding flows and intercompany arrangements.
In addition, established companies sometimes have historical layers of rights and agreements, such as shareholders’ agreements, preferred shares, options and more. A flip carried out without proper mapping and coordination of documents may create disputes, delays or difficulties in future transactions.
Another potential drawback is exposure to estate tax or inheritance tax in the foreign jurisdiction. For example, holding shares in a U.S. company may create exposure to U.S. estate tax even for a shareholder who is not a U.S. citizen or resident. The application of such tax depends on local law, the type of company and the circumstances of the shareholder. It is therefore important to examine this issue already when choosing the jurisdiction of incorporation. In addition, the new structure requires management and reporting for an additional company and may increase ongoing costs.
Flip, Transfer Pricing and Intellectual Property
Beyond carrying out the flip itself, it is important to examine the implications of the new structure already at the planning stage. After a flip, a group of related parties is usually created, for example a foreign parent company and an Israeli operating or technology company. In this situation, questions arise regarding transfer pricing, intercompany agreements, pricing of services, use of intellectual property, management fees and allocation of expenses. When these matters are structured properly, the new structure can support the group’s international activity and reduce friction later on.
In particular, where the substantive activity remains in Israel, it is important to ensure that the documents, agreements and actual conduct are consistent with one another. Otherwise, questions may arise not only from a tax perspective, but also from corporate, accounting and commercial perspectives.
A flip can be an important business tool for Israeli companies where there is a real need for an international structure, for example for raising capital from foreign investors, commercial engagements, global growth, group reorganization or preparation for a future transaction. When planned and implemented correctly, it can help create a clearer corporate platform, make it easier to work with foreign investors and partners, and support the company’s business development.
Alongside the potential advantages, this is a process that requires a precise review of tax, holding structure, corporate documentation, intellectual property, transfer pricing and future implications. Therefore, if you are considering a flip, it is advisable to examine the matter at an early stage in order to build a practical, efficient and well-supported process that advances the company’s business goals.
Why Carry Out a Flip with Us?
Nimrod Yaron & Co. specializes in Israeli and international taxation and has experience in advising on all stages of a flip and in working with the Israel Tax Authority. Our team consists of professionals with years of experience at the Israel Tax Authority, alongside experience in leading accounting firms and law firms, bringing together a legal and economic perspective. We advise private and public companies, Israeli and foreign companies and global venture capital funds, and coordinate the tax work with the trustee and with lawyers in Israel and abroad. Our professional network enables us to assist in coordinating the broader support required in cross-border matters.
We know that the most urgent question for the company and its investors is often: how long will it take to complete the process? For this reason, our focus is on moving the process forward quickly and in a coordinated manner: identifying obstacles in advance, preparing a complete application, coordinating early with the trustee and advisers, and advancing tasks in parallel wherever possible. Our experience is intended to reduce avoidable rounds of follow-up requests and delays, so that the flip does not become an obstacle to the financing round.
The duration of the process also depends on the complexity of the company, the availability of documents and signatures, and the handling by the Israel Tax Authority and the parties abroad. We cannot guarantee an approval date that is not under our control, but we work to manage the process efficiently, while monitoring tasks and aligning the work with the company’s business timeline.
If you are considering a flip ahead of a financing round, the entry of an investor, a listing or a group reorganization, it is advisable to carry out a focused feasibility review at an early stage. Such a review can help clarify the possible tax framework, which documents need to be prepared, and how to properly address intellectual property and transfer pricing matters. We would be pleased to schedule a strategic consultation and build a practical action plan for you based on the company’s position and business goals.
Frequently Asked Questions
Is a flip suitable only for startups?
No. Although it is very common among startups, established companies and international groups also use it for reorganization, the entry of foreign investors, the creation of a global holding company, the consolidation of international activity, or preparation for a listing or transaction abroad.
Does a flip require transferring activity out of Israel?
Not necessarily. In many cases, the substantive activity – employees, development, operations or services – remains in Israel, while the change takes place at the holding-company level. This is one of the important features of a flip, and sometimes one of the factors that makes it a relevant solution for companies that wish to expand internationally without moving the center of activity out of Israel.
Is there always a tax advantage?
No. In certain circumstances, tax deferral may be available, but not in every case and not at any cost. In addition, future implications must also be examined, including distributions of profits, dividends, intercompany payments and transfer pricing. The benefit of the transaction is therefore assessed not only on the implementation date, but as part of the overall business and tax picture.
Is a new foreign company always required?
Not necessarily. In certain cases, the transaction can also be carried out using an existing foreign company, subject to the holding structure, the identity of the shareholders and the relevant legal and tax conditions. The choice between a new company and an existing company depends on the specific circumstances and the group’s business objectives.
Is the green track suitable for every case?
No. This route applies only to cases that meet defined conditions, and it sometimes includes ongoing restrictions and material reporting obligations. Form 982 is intended for a defined structure involving the transfer of all rights in a private Israeli company to a private company resident in a treaty country, incorporated specifically for the purpose of the transaction. The company’s eligibility for the route and the wording of the application should be reviewed in light of the updated law, and in particular the 2025 legislative amendments. Where the conditions are not suitable, an individual application should be considered.
Can a flip be carried out without professional guidance?
Technically, such a process can be advanced, but in practice it is a complex restructuring with tax, corporate, documentation and international operational implications. In most cases, it is highly advisable to carry it out with appropriate professional guidance, in order to reduce risks, address complexities in advance and build a proper, efficient and durable structure.
What points does the Israel Tax Authority tend to examine?
Typically, it examines rights and holding percentages, value on the transaction date, substance and business purpose, and documentation. In addition, after a flip, there are sometimes reviews of transactions between related companies – services, intellectual property (IP), royalties, management fees and other payments – and whether they are priced at arm’s length and documented in agreements that correspond to the actual activity.